

Here’s a test for any innovation unit.
If your team vanished tomorrow, which business unit would complain?
It has to be a business unit with a P&L, one that would feel the loss on Monday morning. CEO sponsorship doesn’t count. Sponsors leave, and the next one shows up with a spreadsheet and a cost target.
Last month in London, a room full of people who run corporate venture units kept landing on the same pattern. The units that survive are wired into the business, into sales, BD, three or four business units at once, each running a project they’d miss. Too many people depend on them for a new CEO to quietly delete them. The ones that die were only ever the CEO’s project, a line item nobody else would defend.
Look at PayPal Ventures.
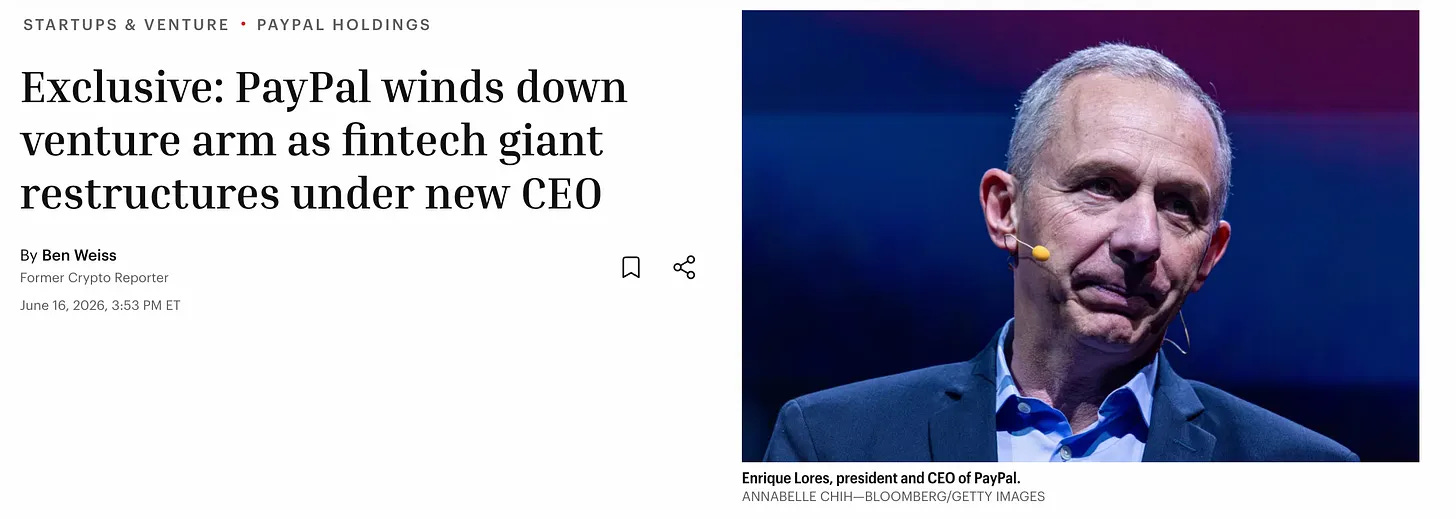
Ten years old. More than 80 companies backed across three funds, $850 million deployed. Early bets on Plaid and Anchorage Digital. And in the fourth quarter of 2025, the portfolio added 10 cents to PayPal’s earnings per share. It was making money.
In June 2026 it wound down anyway. Enrique Lores became CEO in March with a mandate to cut $1.5 billion over two to three years and recommit to core payments. The venture team went from more than 10 partners to two. What’s left is being sold on the secondary market.
So a profitable venture arm still got cut. Financial returns didn’t save it, and board-level visibility didn’t either. The fund invested off PayPal’s balance sheet, which is clean and independent, and also means no single business unit woke up that morning having lost something it relied on. Nothing was load-bearing.
So does the answer lies in being more ‘strategic’? In the GCV room, the standard line, “we’re purely strategic, we don’t chase returns,” got pushback: a fund that can’t point to returns looks like pure cost on any EBITDA review. PayPal shows the other side of the same coin.
My view: A unit survives when it’s impossible to remove without breaking something the core business relies on. Returns help. Visibility helps. Neither is the thing.
Anyway, PayPal is not alone
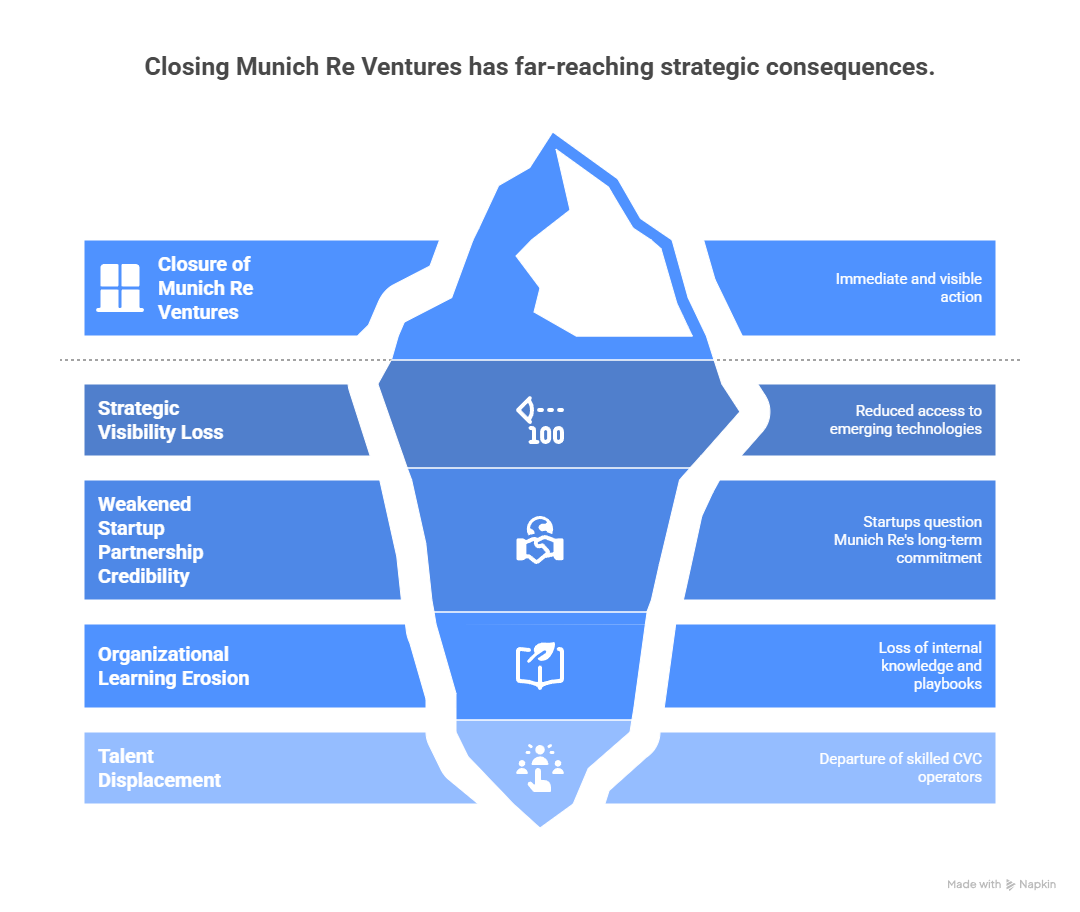
The same month, Commerzbank closed Neosfer after 13 years. Weeks earlier, Fidelity International sold off its strategic venture arm. Munich Re is winding down its $1.2 billion Munich Re Ventures. ING halted new investments in 2025. Go back further and it’s a genre: BBVA, Santander and ABN Amro all pushed their venture teams out.
Easy to read that as retreat. It isn’t. 2025 was venture’s strongest year since 2021, with corporates in 68% of global AI deal value, according to Bain. Corporate venture is splitting in two. For Nvidia and Meta, backing startups is core strategy funded off a huge balance sheet, so it survives budget season. For everyone else it’s one priority fighting the core business for the same money.
As the investor Steve Brotman put it, size protected neither PayPal nor Fidelity; the dividing line runs through the mandate. Nvidia’s business depends on its bets. PayPal’s board decided theirs didn’t.
Why the fragile version keeps getting built
Most corporate venture units aren’t born from a business need. They’re born from pressure to look like everyone else. Researchers call this institutional isomorphism, an idea from DiMaggio and Powell in 1983, and they name three forces behind it:
Coercive is pressure from above or outside. A regulator, a government grant that requires collaboration, a board that has decided the company needs an innovation story for the annual report. Someone with power says “we should have one of these,” so you build one.
Mimetic is copying your peers when nobody’s sure what actually works. Siemens has Next47. A competitor just announced a fund. So you announce one too, because standing still looks worse than following. Under uncertainty, imitation feels like the safe bet.
Normative is professional fashion. Business schools teach open innovation. The Chief Innovation Officer title exists. There’s a whole circuit of conferences and certifications behind it. The role gets created because the profession says the role should exist.
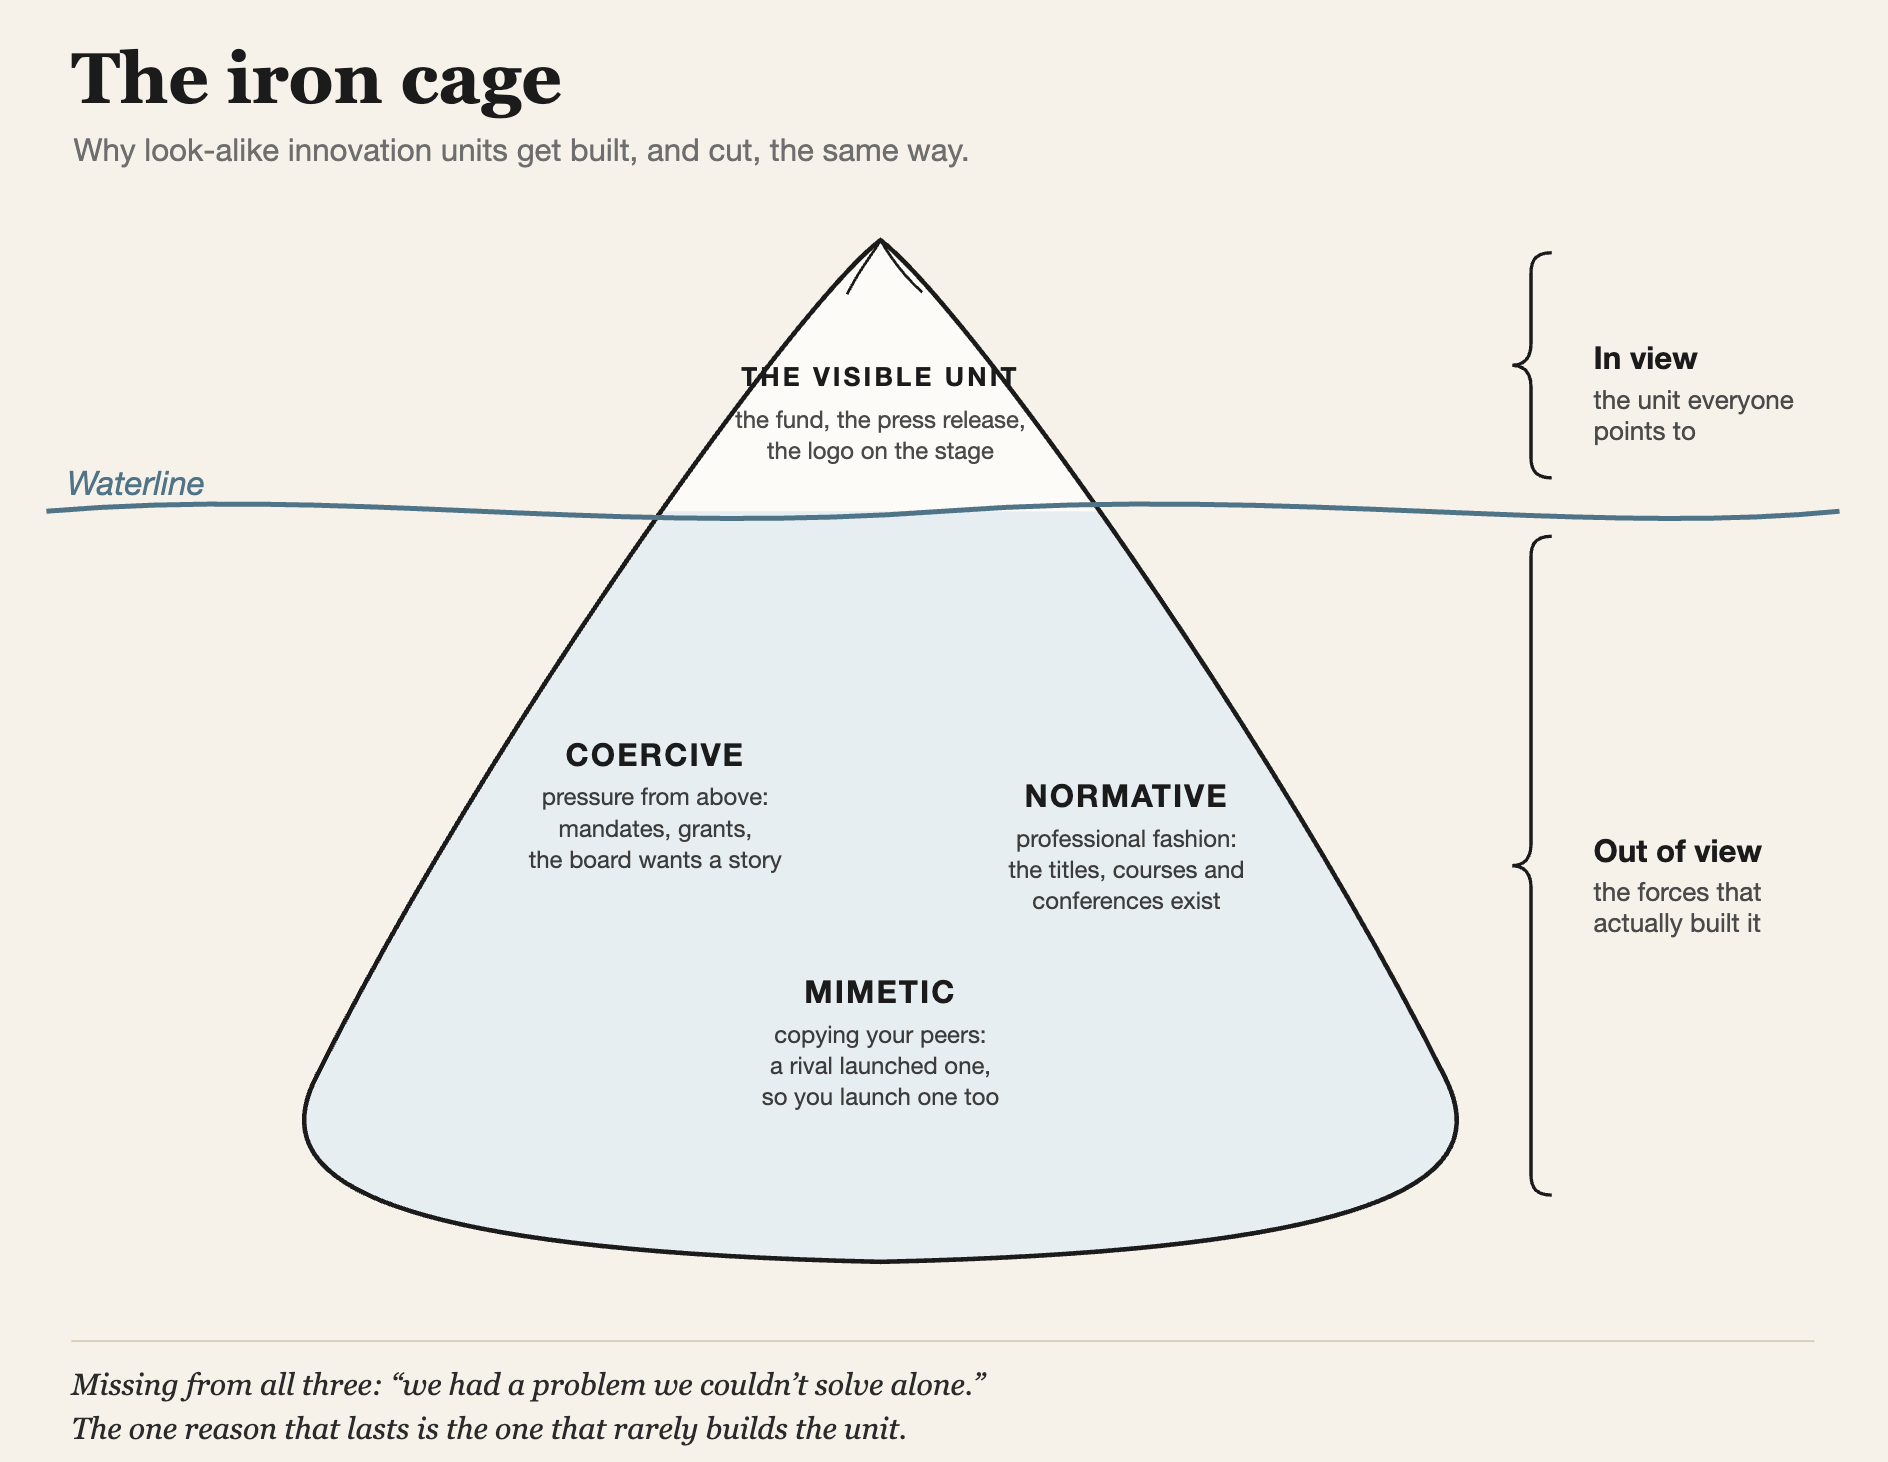
Now read what none of those three is. None of them is “we had a problem we couldn’t solve alone, so we went outside to solve it.” That’s the only durable reason to build one of these units, and it’s the one that rarely gets it built.
A unit that exists because everyone else has one has no anchor. So when the fashion shifts to AI, or the board wants a fresher story, or a new CEO wants to look decisive, it goes. What gets adopted because everyone adopted it gets dropped the same way. The herd moves. Nothing underneath was carrying weight.
Make it expensive to remove
So what’s the fix? It’s, as usual, a design problem.
Solve one real problem for one real business unit, and put them on the hook with you. A few levers separate the units that survive a leadership change from the ones that get cut.
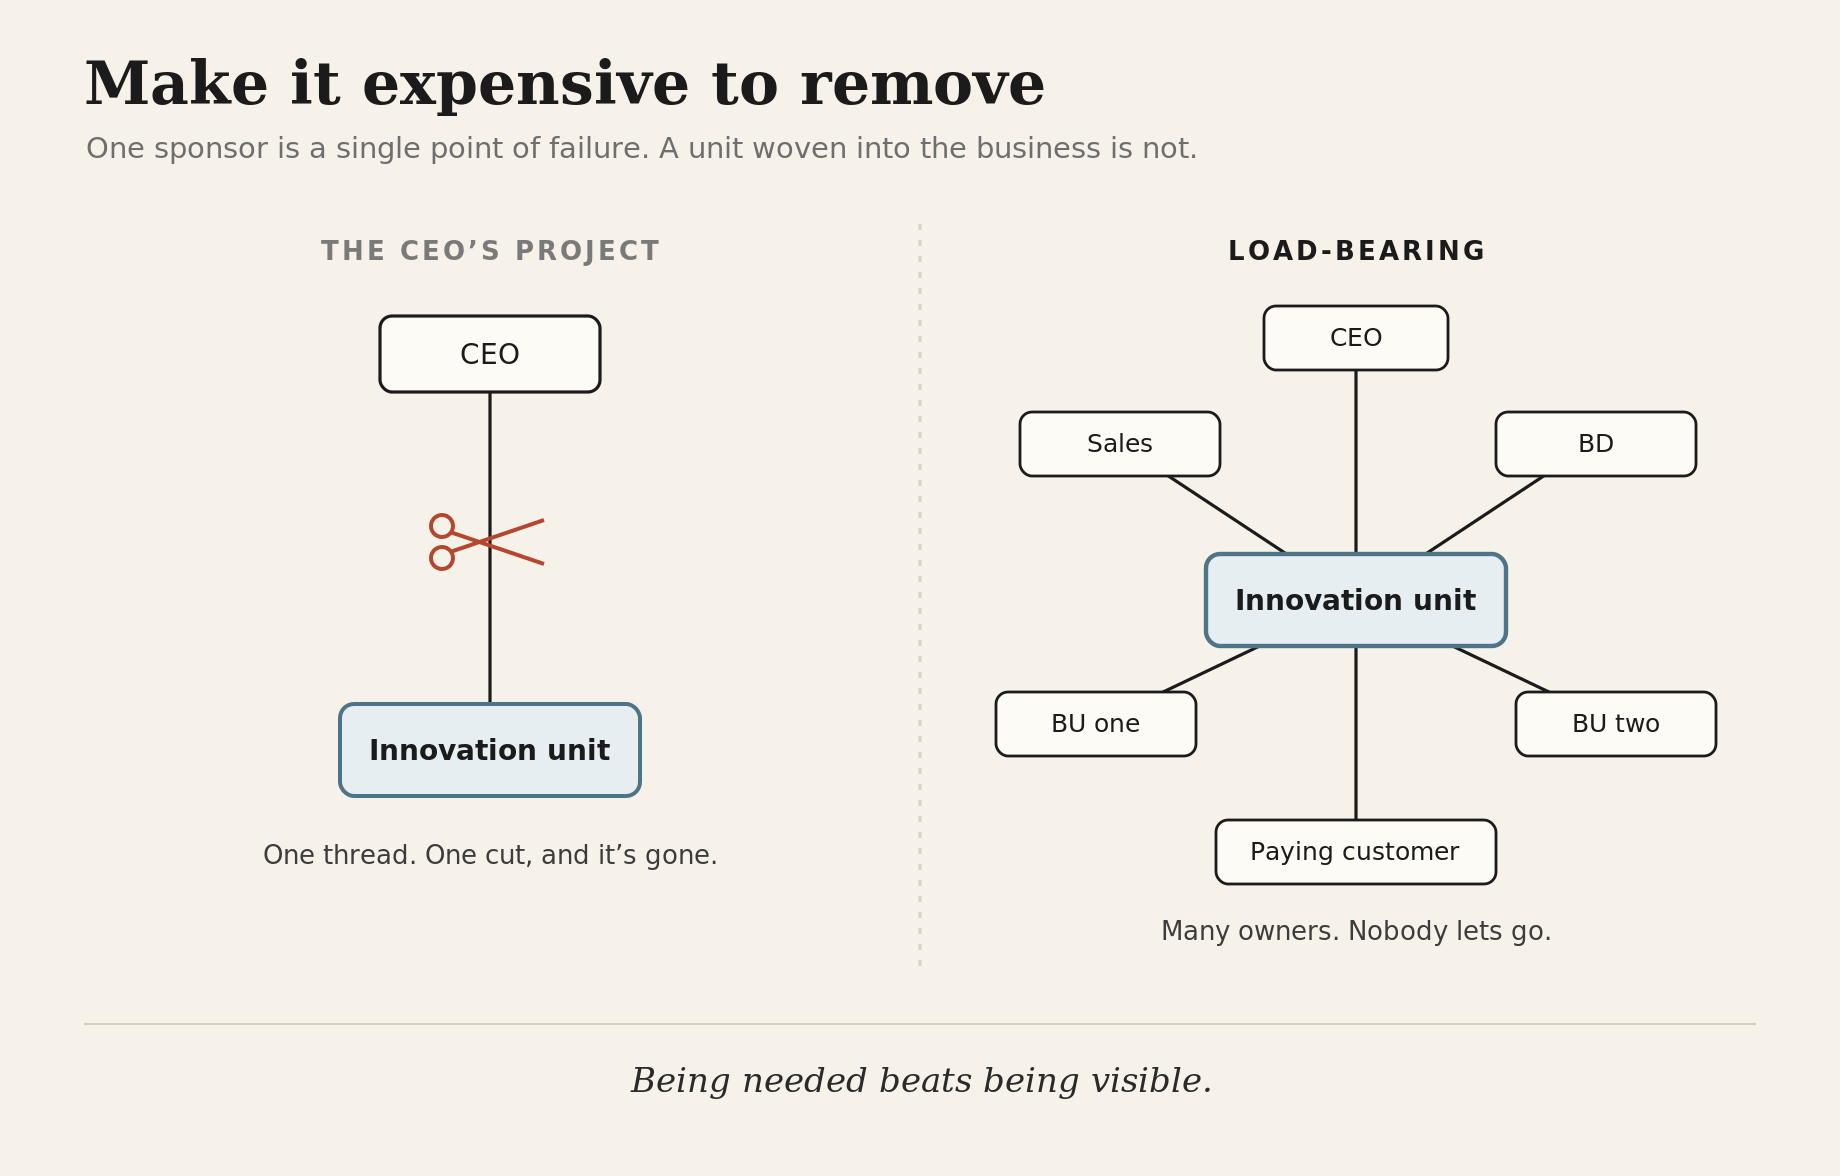
Start with how it’s funded. The people who run these funds treat structure as a survival tool. An annual budget is the easiest thing in the world to cut, gone in any planning cycle. Committed capital is harder to claw back. A fund backed by two non-competing companies from the same industry is hardest of all, because killing it means unwinding someone else’s commitment too.
Then embed it. The pharma model gets cited as the template. The venture team takes equity in a startup while the BD team runs a licensing deal on the same asset. Two internal teams, both bought in, both with something to lose if the unit disappears. One automotive team I heard from runs off a single sentence: invest in startups that accelerate the parent’s strategic transformation. That one line outlasted three CEOs in four years, because every incoming boss could read it and see their own agenda in it.
The strongest position is to be both an investor and a customer. Microsoft’s Climate Innovation Fund does this in the open, backing climate startups and buying from them, so the startup has a reason to want Microsoft on its cap table and an internal team has a reason to defend the relationship.
There's a fourth move, and it might be the sturdiest: make startups your customers. AWS and NVIDIA don't run their startup programs out of goodwill. Today's startup is tomorrow's big spender. NVIDIA Inception has taken in more than 40,000 AI startups, free to join, because each one is a future GPU buyer. AWS has handed startups over $6 billion in credits since 2020 for the same reason. A program like that survives every downturn because it sits inside the revenue engine. It's customer acquisition wearing a startup-program badge, and sales will always fight for it.
Venture Clienting, the lucky kid on the block
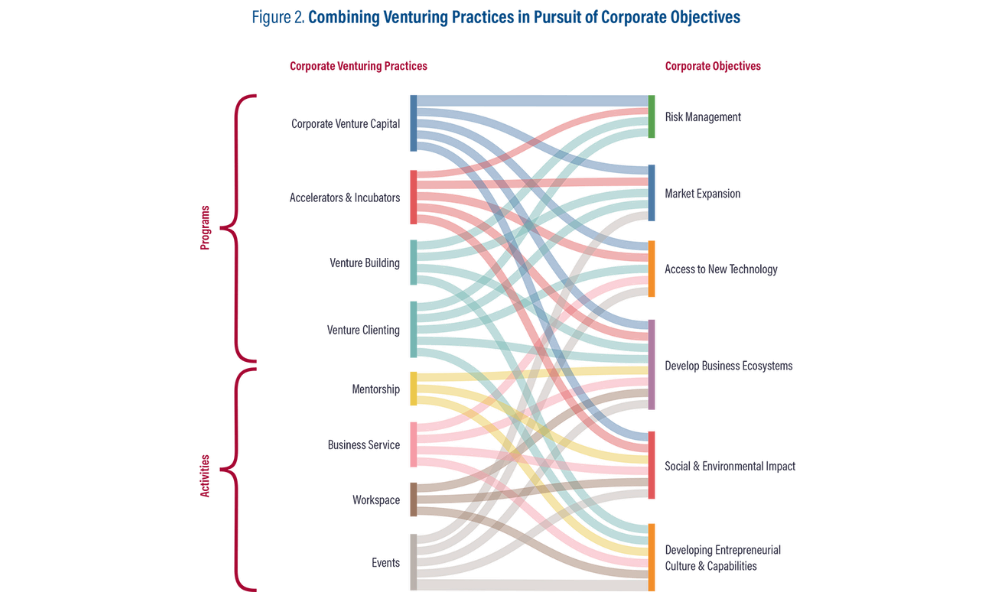
This is where venture clienting earns its keep. You bring a startup in as a paying customer to fix a problem a team has right now, instead of buying equity and waiting years for a strategic return that may never land on anyone’s desk.
The mechanic that makes it stick is ownership: people from the business help scout the startups, score them, and sit in the pilots, so they feel like owners rather than spectators.
Some funds now make a proof of concept within six months a condition of investing, so a BU is committed before the check clears. When a pilot moves a number a BU actually cares about, that BU fights to keep you. The fight is your insurance policy.
Venture building sits at the hard end of all this. A build unit spins up new companies from scratch, usually next to the core business rather than inside it, betting on things that don't exist yet. That's the catch. It doesn't fix a problem any business unit has this quarter, so no internal team wakes up needing it.
Venture Clienting doesn’t photographs well. It’s slower than a unicorn logo on a board slide, and it wins fewer conference stages. It’s also the only version still standing when the CEO changes.
But, being needed beats being visible.
One question for your own unit. If it vanished tomorrow, who would protest? If the honest answer is “the CEO,” you have work to do before the next cost target lands.
Thanks for reading this, see you next time!
Davide
Did you enjoy this edition? Share it with anyone you like and give it a heart. Subscribe to receive Open Road Ventures’ posts every week.
A soundtrack to accompany your reading: